FaceTime Like a Pro
Get our exclusive Ultimate FaceTime Guide 📚 — absolutely FREE when you sign up for our newsletter below.
FaceTime Like a Pro
Get our exclusive Ultimate FaceTime Guide 📚 — absolutely FREE when you sign up for our newsletter below.
Counterpoint says Apple took 37% of Europe's carrier channel in Q2, passing Samsung as operator sales proved more resilient than the broader phone market.
Apple passed Samsung to lead Europe’s smartphone operator channel in Q2 2026, even as phone sales fell across the region. Counterpoint Research says sales through mobile operators fell 4% year over year, compared with an 11% decline in the open market.
The lead applies only to carrier sales. Counterpoint links the channel’s relative strength to its premium-device mix and the pressure rising memory costs have put on cheaper phones.
Total smartphone sales in Europe fell 8% year over year in Q2, according to Counterpoint. Sales through operators declined by 4%, while the open market, which includes sales outside carrier channels, fell 11%. That gap helped operators gain share of the market, even though they also sold fewer phones than a year earlier.
The channel mix helps explain why. Counterpoint says carrier sales tend to include more high-end phones and premium brands because more devices are bought on contract. Meanwhile, higher memory costs have hit the low end of the market particularly hard. The operator channel has weathered the downturn better, but its sales still fell.
Apple’s share of smartphone sales through European operators rose from 33% in Q2 2025 to 37% in Q2 2026, according to Counterpoint figures cited by 9to5Mac. Samsung’s share fell from 39% to 34% over the same period. Apple gained four percentage points while Samsung lost five.
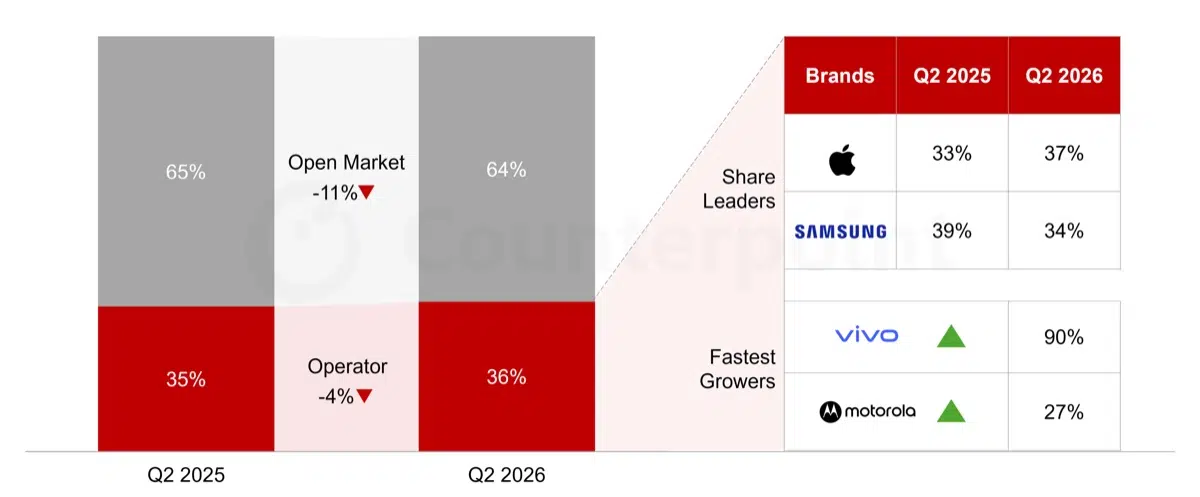
Those shares show each brand’s portion of operator sales, not the number of phones it sold. Since the channel shrank 4%, Apple’s bigger share alone cannot show whether it sold more phones through carriers. Counterpoint’s public summary does not give brand-level unit totals.
Those figures apply only to carrier sales. Counterpoint’s separate estimate of all European smartphone shipments put Apple and Samsung at 34% each in Q2. Shipments and sales through operators measure different parts of the market, so Apple’s carrier-channel lead does not mean it led overall European shipments. In the global market, Q2 shipment rankings also put Samsung ahead of Apple.
Counterpoint also says vivo and Motorola helped the operator channel, with both brands growing faster than the market. The public report does not break out the country-level figures or say which phone models drove Apple’s gain.
Counterpoint expects the operator channel to continue gaining share over the next few quarters if memory-price pressure keeps hurting lower-cost phones. Independent retailers have increased promotional activity, however, which could soften price increases and help the open market recover some demand.
The Q2 data show Apple’s lead in one sales channel, not a wider recovery in Europe’s smartphone market. They also do not tell buyers whether one carrier has better iPhone deals; Counterpoint tracks channel sales, not individual offers.